 TradeScope
Strategy Lab
Keep every Strategy Analyzer backtest, charge it at your real costs, and compare runs side by side.
Applies to TradeScope 2.4 · Updated September 2026
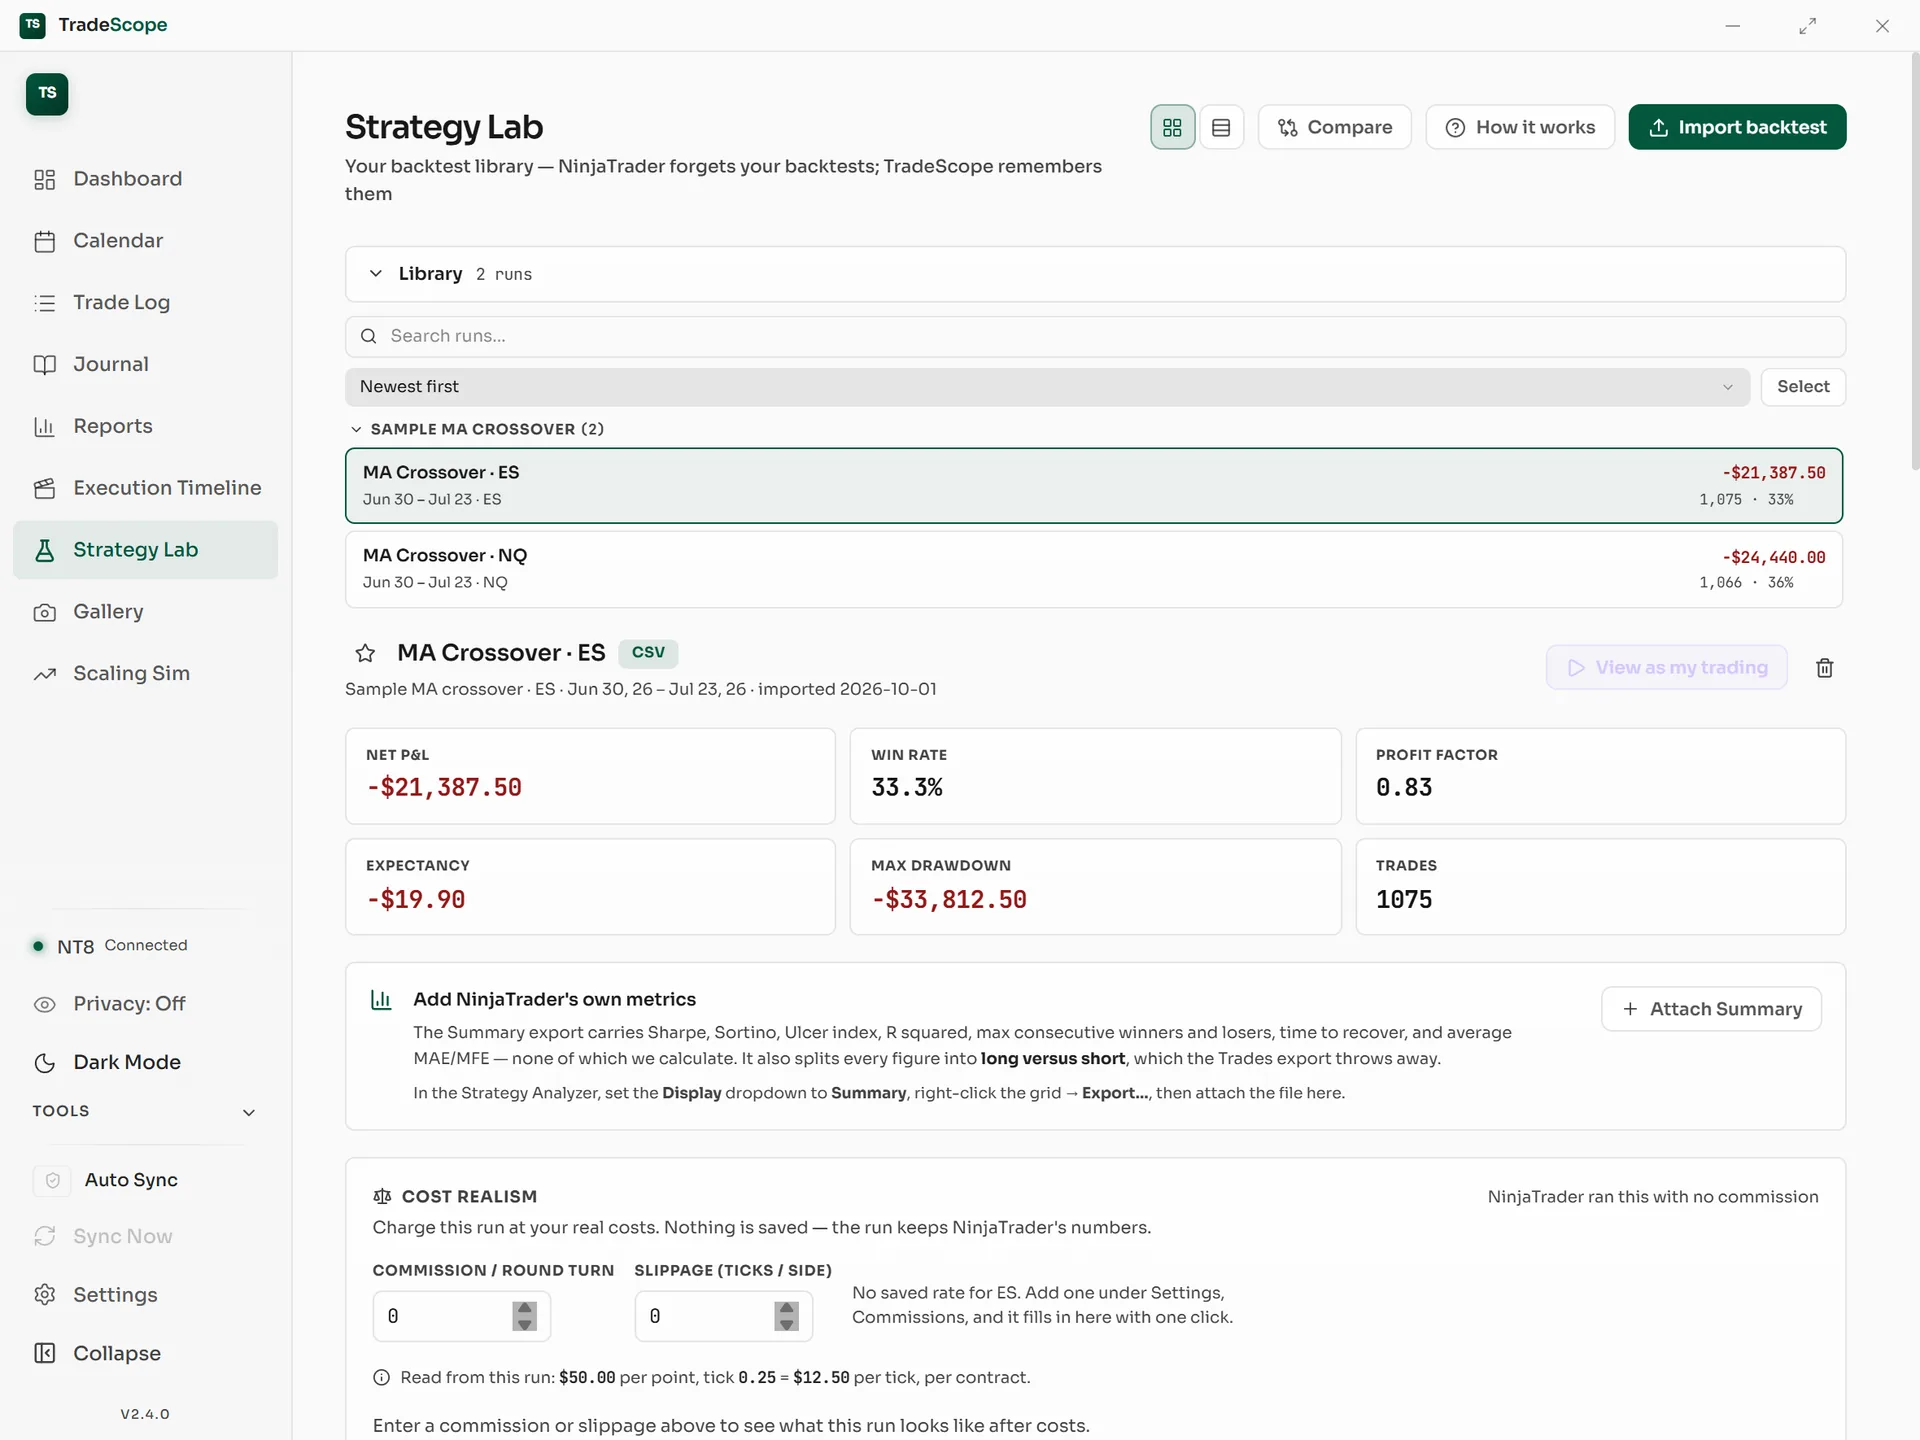
NinjaTrader forgets a backtest as soon as you close the Strategy Analyzer. The Strategy Lab keeps them. Import a backtest once and it stays in your library, with the same stats and charts you get for your real trading.
The Lab doesn’t build, optimise or run strategies. NinjaTrader does that. The Lab is where the results live afterwards. Backtests are kept separate from your real trades and never mix into your statistics.
Exporting from NinjaTrader
- In NinjaTrader, open Control Center → New → Strategy Analyzer.
- Pick your strategy, instrument and dates, then click Run.
- Change the Display dropdown at the top left from Summary to Trades.
- Right-click the trades grid, choose Export…, and save it as a CSV file.
Importing a backtest
- Open Strategy Lab in the sidebar and click Import backtest.
- Choose the CSV file.
- Check the preview: number of trades, net P&L, commission and date span. Give the run a name.
- Click Import.
If something’s off, the preview says so. A missing column comes with the fix: in NinjaTrader, right-click the trades grid, open Properties → Columns – Trades, turn the column on, and export again. If you exported the Summary grid by mistake, TradeScope tells you.
Adding NinjaTrader’s own metrics
The Trades export doesn’t include ratios like Sharpe and Sortino. To add them:
- In the Strategy Analyzer, set Display back to Summary, right-click and Export….
- On the run’s page in TradeScope, click Attach Summary and choose that file.
The run then shows Sharpe, Sortino, Ulcer index, R squared and Probability, a long-versus-short split, and every metric NinjaTrader reported. These are NinjaTrader’s figures, shown as-is. If the Summary doesn’t match the run, TradeScope warns you before attaching it.
A run’s page

Each run shows net P&L, win rate, profit factor, expectancy, max drawdown and trade count, followed by its equity curve, P&L by hour and by day of week, P&L distribution, and MAE/MFE. There are two notes boxes, Strategy parameters and Decision trail, for the settings you used and why you kept or dropped the idea.
View as my trading shows the backtest across the Dashboard, Calendar and Reports, as if you’d traded it. A banner reminds you that you’re looking at a backtest. Click Back to my trading to return.
Cost realism
Backtests are often run with no commission or slippage, which flatters them. The Cost realism card charges the run at your real costs:
- Commission / round turn, or pick My default rates or one of your broker profiles
- Slippage (ticks / side)
The card shows each key stat before and after, and how many winning trades turn into losers once costs are paid. Nothing is saved: the run keeps NinjaTrader’s numbers.
Your library
- Search runs, sort them, and star the ones you want at the top.
- Runs are grouped by strategy name. Switch between card and table view.
- Compare puts two to four runs side by side, with their equity curves and a head-to-head table that highlights the best value in each row.
- Select lets you star or delete several runs at once. Deleting is permanent, and NinjaTrader has no copy.
Prop firm rule replay (experimental)
Turn this on in Settings → General → Experimental → Prop firm rule replay. Each run then gets a Prop firm rules card that replays the backtest against an evaluation’s rules: profit target, drawdown, daily loss limit, minimum trading days and a consistency rule. It tells you whether the run would have Passed, blown the account and on which day, or survived without reaching the target.
Start from a template or make your own rule set. Templates are a starting point, not any firm’s official terms. Firms change their rules, so check yours before relying on the result.
Still stuck? Contact support. A real person answers.